All Categories
Featured
Corporate Banking Developments Impact British Business Growth
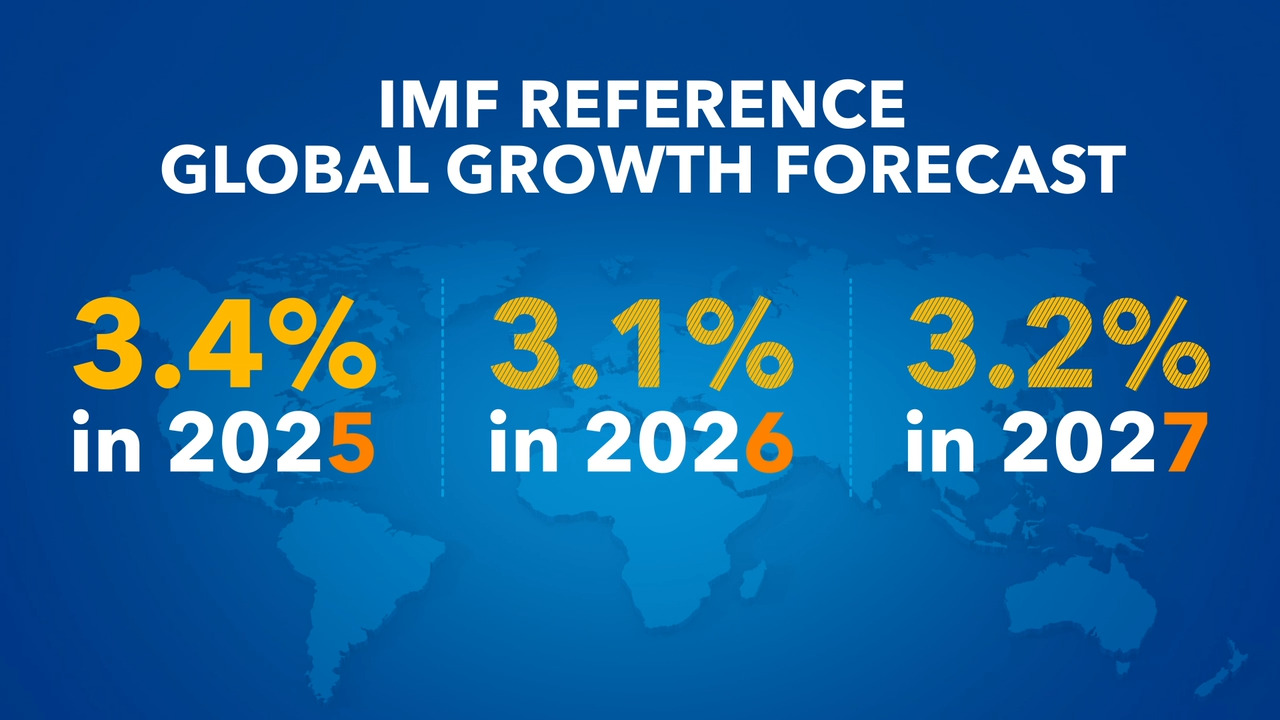
The UK is particularly exposed given its dependence on gas for electrical power rates, which is why the International Monetary Fund (IMF) has actually revised its UK inflation and development forecasts more greatly than any other developed economy. Inflation briefly dipped below 3% for the very first time since early 2025, however the reprieve will be short-term.
A weaker labour market and softer need need to prevent a repeat of 2022's double-digit spike, limiting second-round effects. Our base case is inflation balancing 3.1% in 2026, peaking around 3.5%, before easing to 2.5% in 2027, though dangers loom big if the Strait of Hormuz stays closed. The UK labour market was currently softening before the most recent energy shock, with unemployment increasing to 5.0% and jobs at their least expensive because the pandemic.
Sustainable Capital Versus Debt in the UKFirms are not yet shedding staff, but hesitation to hire is broadening the gap between job development and population development. Greater energy costs will compound the pressure, and we anticipate joblessness to peak at 5.3% by year end. With wage growth slowing to around 3.75% and inflation heading towards 3.5%, real pay looks set to be stagnant another difficult year for living requirements.
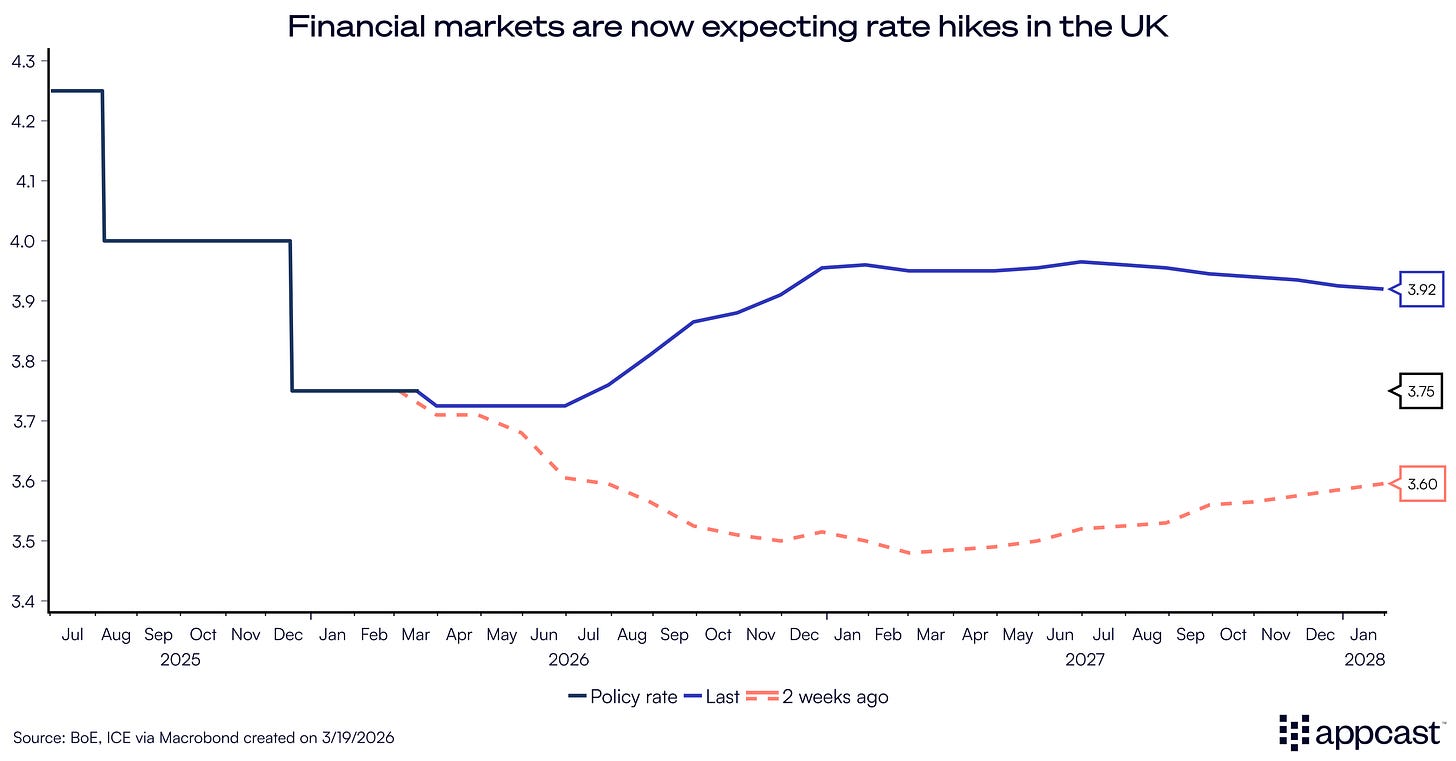
Sustainable Capital Versus Debt in the UK3 factors restrict the case for walkings: the energy shock is smaller than in 2022, rates are currently at a restrictive level, and a weaker economy lowers the danger of second-round inflation impacts. That stated, rate rises can not be ruled out if energy prices surge further. Gilt yields are most likely to stay elevated regardless, driven by the UK's inflation sensitivity and political unpredictability around a potential modification of Prime Minister, keeping borrowing expenses high across the economy even if the policy rate stays on hold.

Latest Posts
Maximizing Capital with UK Investment Vehicles

Future-Proofing UK Talent Strategies in 2026
Is Your British Business Prepared for Global Expansion?